Independent California insurance brokerage562-COVWELL   Agency 6013787
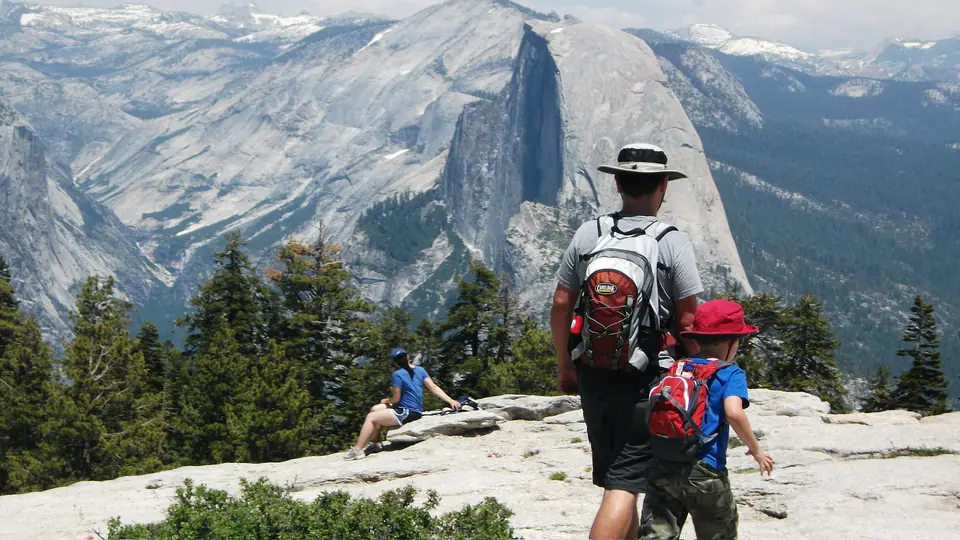
The Bollinger family together in Yosemite

For financial advisers and wealth managers

Keep the insurance file aligned with the plan around it.

Give a complex client one organized view of property, liability, business, life-insurance, ownership, and renewal work. The client controls the file, a named licensed broker owns the next action, and your investment, tax, legal, and estate-planning roles stay clear.

One client. One page. Two business days after usable documents. No charge or broker change required.

Three generations in California insuranceNamed licensed broker5.0 on Google, 20 reviews

The private-client continuity file

A useful insurance deliverable, not another referral promise.

Start with one active client at no cost and without changing brokers. Bollinsure organizes the insurance evidence, names the open work, and says plainly when the current program appears to be the right path.

Coverage inventory
Homes, vehicles, valuables, umbrella, domestic staff, businesses, and life coverage organized by source and renewal.
Ownership alignment
Named-insured, trust, LLC, entity, beneficiary, and insurable-interest questions surfaced for the proper professional to resolve.
Event-trigger worklist
Property purchases, liquidity events, new drivers, business changes, succession, and renewal deadlines converted into next actions.
Permissioned status
The adviser sees only the status the client authorizes; policy details remain private by default.

When a liquidity event, a new residence, trust ownership or board service changes the picture, Bollinsure produces a private client continuity file organized by source and renewal so you can keep the insurance file aligned with the plan around it — without making you the insurance coordinator or asking the client to change brokers.

The deliverable

What your client actually receives.

One page, every line tied to the record that produced it, and a named licensed broker behind the next action. Synthetic sample. No real client, carrier, premium, eligibility or placement is shown, and nothing here is a coverage conclusion.

Private Client Continuity FileThe Ellison household · synthetic sample
Annual review
Residences
Two; the Montecito home is held in the family trust
Client confirmedConfirmed
Named insured on that policy
An individual, not the trust
Policy supplied · page 1Open question
Umbrella attachment
$2M over an auto limit that dropped at renewal
Policy supplied · page 3Broker review
Board service
One outside directorship, no personal D&O located
Client confirmedOpen question
Reviewed next action

Align the named insured with how the residence is actually held, then re-check the umbrella attachment point.
Bollinsure · in 5 days

Private-client continuity file

Show the client what is covered, what changed, and who owns the next step.

This synthetic example shows the deliverable, not a promise of automatic coverage analysis. Sources stay attached, suggested facts require confirmation, and a licensed broker reviews insurance conclusions.

Review one client →
Private Client Continuity FileSynthetic household · adviser view demonstration
Broker reviewed
Insurance areasPersonal · Business · Life
Next renewal63 days
Open actions4
Adviser accessStatus only

Coverage inventory

The client sees the whole insurance file.

Homes and valuables
2 residences · collection scheduled
Source linked
Vehicles and liability
3 vehicles · umbrella review
Client confirmed
Business interests
GL, cyber, EPLI, key person
Broker review
Life insurance
Ownership and beneficiary check
Separate lane
No account statements neededNo broker change requiredStay-put answers are valid outcomes

The no-cost pilot

One client. One page. Two business days.

  1. 01
    Introduce one client

    Send a name, the trigger and the deadline. No client documents, and no referral agreement, broker change or minimum volume.

  2. 02
    A named broker takes ownership

    We acknowledge the file the same business day, contact the client directly, and organize the usable documents and available records against the real deadline.

  3. 03
    The client receives the one-page worklist

    Within two business days after usable documents arrive, the client sees the open issues, sources, deadline and next owner. You see only the status the client authorizes.

What this is not. Not instant analysis, and not a guarantee that every gap is found. Extracted, public-record and provider values are suggestions until the client confirms them. Carrier eligibility, terms, pricing and binding are underwriting decisions, and only an issued carrier or agency document confirms coverage. Bollinsure gives no legal, tax or accounting advice.

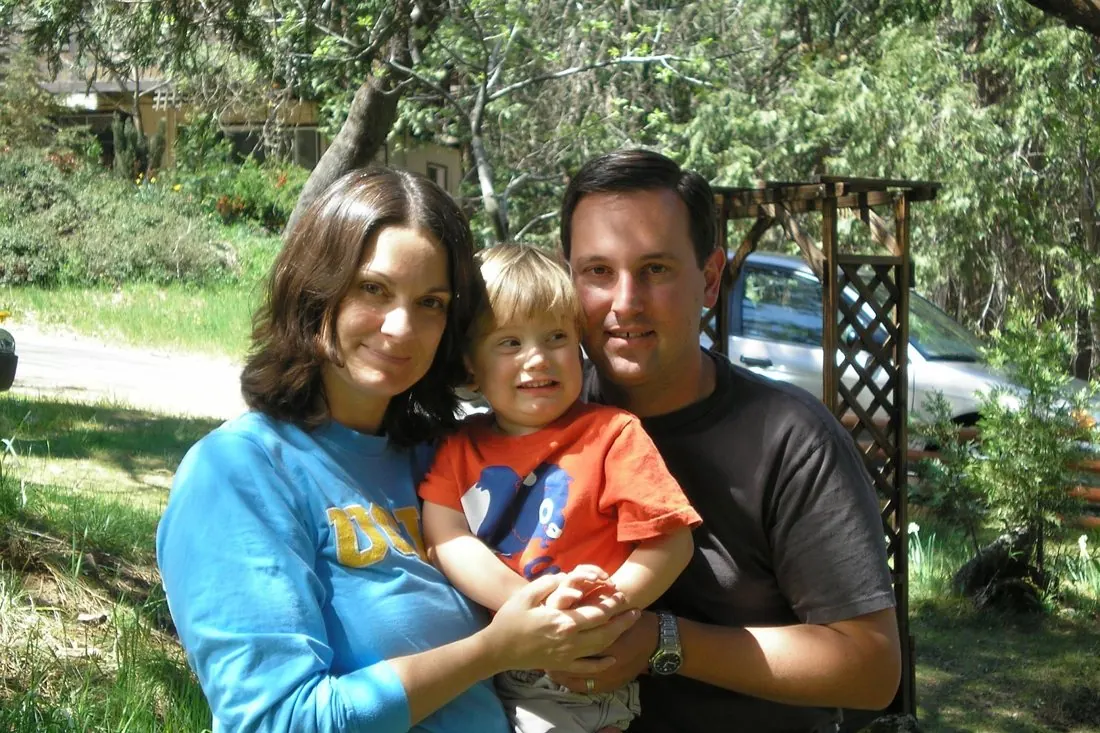
The Bollinger family together in California
A family-owned California brokerage, with a named person responsible for the answer.

Technology with an accountable owner

The workspace organizes the file. A licensed broker owns the insurance work.

Automation can locate facts, compare records, and keep deadlines visible. It does not bind coverage, decide a claim, or turn a public record into underwriting truth. Bollinsure keeps those boundaries visible and gives the client one responsible place to ask what comes next.

No-cost one-client pilot

Try the private-client continuity file on one active situation.

Tell us the kind of client situation and when it matters. No client name or files are needed here. Bollinsure will reply with the sample continuity file, a short pilot scope, or a client-included introduction.

  • No-cost one-client pilot
  • No broker change or minimum volume
  • Named licensed broker
  • Client-controlled partner visibility

Do not enter a client name or paste confidential records here. Bollinsure will provide the appropriate client-included introduction or secure document path after reviewing the request.

Common questions

A clean professional boundary.

What happens when I introduce a client?

A named licensed Bollinsure broker establishes the insurance scope directly with the client, gives the client a written next action, and shares limited status with the referring professional only when the client permits it.

What information is needed to begin?

The client or business name, the insurance trigger, and any real deadline are enough to start. Sensitive financial, medical, employee, or account records are not needed for the initial handoff.

Does the partnership require referrals or compensation?

No referral fee, reciprocal introduction, or production commitment is assumed. Any proposed compensation arrangement must be reviewed and documented separately before use.

Will Bollinsure give investment, tax, or estate-planning advice?

No. Bollinsure owns the insurance analysis only. The client's financial, tax, legal, and estate advisers retain their respective roles.