Independent California insurance brokerage562-COVWELL   Agency 6013787
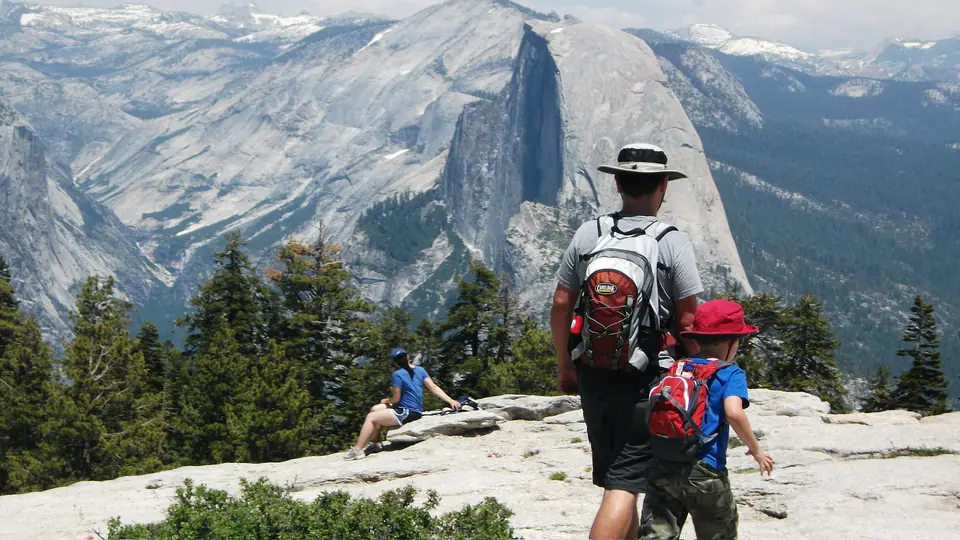
The Bollinger family together in Yosemite

For real estate and mortgage professionals

Find the insurance path before it becomes the reason a home cannot close.

Bollinsure helps buyers and homeowners address property eligibility, wildfire exposure, replacement cost, lender requirements, and connected liability coverage while the transaction still has room to move.

One client. One page. Two business days after usable documents. No charge or broker change required.

Three generations in California insuranceNamed licensed broker5.0 on Google, 20 reviews

The closing handoff

A property-readiness view, a deadline owner, and an honest status.

The client receives a direct insurance path. The professional receives appropriate status only with permission, and a request for evidence is never described as completed underwriting.

Property readiness
Address, occupancy, construction, updates, catastrophe exposure, and current coverage put in scope.
Lender requirements
Mortgagee, replacement-cost, deductible, and evidence requests organized for the insurance file.
Connected coverage
Home, auto, umbrella, landlord, flood, and earthquake questions separated and coordinated.
Stage clarity
Requested, submitted, quoted, bound, and evidenced remain distinct.

When a difficult property, a nonrenewal or a lender deadline creates an insurance dependency, Bollinsure produces a home closing readiness review with an honest placeability read so you can tell the buyer where they stand before escrow hardens — without making you the insurance coordinator or asking the client to change brokers.

The deliverable

What your client actually receives.

One page, every line tied to the record that produced it, and a named licensed broker behind the next action. Synthetic sample. No real client, carrier, premium, eligibility or placement is shown, and nothing here is a coverage conclusion.

Home Closing Readiness reviewA coastal home purchase · synthetic sample
Insurance contingency in 12 days
Year built
Assessor says 1971; the listing says 1968
Public record · conflictOpen question
Roof
Replaced 2019 per the inspection report
Inspection · page 14Confirmed
Brush exposure
Within a mapped high-hazard severity zone
Public recordConfirmed
Likely market path
Admitted market uncertain; surplus lines and FAIR Plan plus DIC are the realistic paths
Broker reviewedBroker review
Reviewed next action

Resolve the build year, then confirm the path. Placeability is not a quote, an eligibility decision or a bound policy.
Bollinsure · in 2 days

What the client receives

Show the experience before asking for the introduction.

A referred client can organize existing coverage, confirm extracted facts, see the open work, and grant a limited status view to the professional who introduced them.

Synthetic demonstration. No real client information is shown. Extracted and enriched values remain suggestions until confirmed; issued policy documents control.

Bollinsure Coverage HubHarbor West Manufacturing · sample file
Broker reviewed
Program overview

Five policies. Three locations. One renewal window.

47 days to first renewal
Annual premium
$48,620
Current documents
Open items
3
Two client, one broker
Confirmed assets
11
3 locations, 8 vehicles
PolicyKey limitRenewsState
General liability$1M / $2MOct 17Client confirmed
Commercial property$6.4M buildingOct 17Broker review
Commercial auto$1M CSLNov 01Carrier issued
Cyber$1M aggregateNov 12Document extracted

The no-cost pilot

One client. One page. Two business days.

  1. 01
    Introduce one client

    Send a name, the trigger and the deadline. No client documents, and no referral agreement, broker change or minimum volume.

  2. 02
    A named broker takes ownership

    We acknowledge the file the same business day, contact the client directly, and organize the usable documents and available records against the real deadline.

  3. 03
    The client receives the one-page worklist

    Within two business days after usable documents arrive, the client sees the open issues, sources, deadline and next owner. You see only the status the client authorizes.

What this is not. Not instant analysis, and not a guarantee that every gap is found. Extracted, public-record and provider values are suggestions until the client confirms them. Carrier eligibility, terms, pricing and binding are underwriting decisions, and only an issued carrier or agency document confirms coverage. Bollinsure gives no legal, tax or accounting advice.

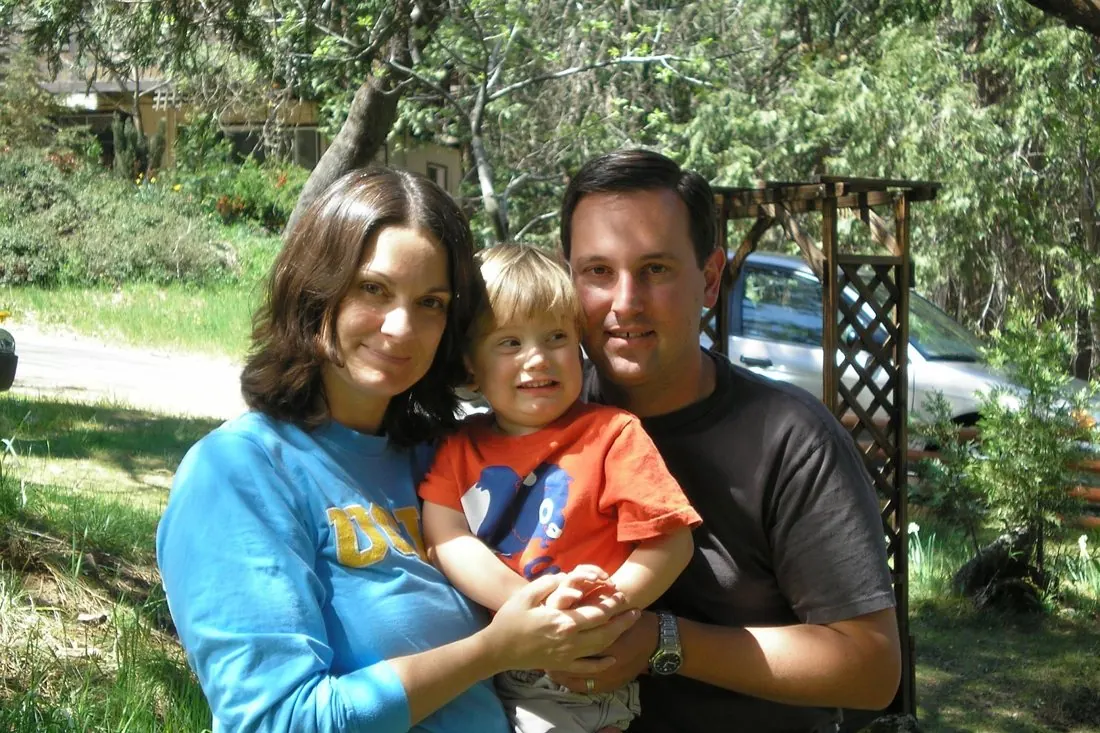
The Bollinger family together in California
A family-owned California brokerage, with a named person responsible for the answer.

Technology with an accountable owner

The workspace organizes the file. A licensed broker owns the insurance work.

Automation can locate facts, compare records, and keep deadlines visible. It does not bind coverage, decide a claim, or turn a public record into underwriting truth. Bollinsure keeps those boundaries visible and gives the client one responsible place to ask what comes next.

No-cost one-client pilot

Try the home closing insurance toolkit on one active situation.

Tell us your role, the recurring insurance problem, and the timing. No client files are needed here. Bollinsure will reply with the safest next step: a sample, checklist, conversation, or client-included introduction.

  • No-cost one-client pilot
  • No broker change or minimum volume
  • Named licensed broker
  • Client-controlled partner visibility

Do not enter a client name or paste confidential records here. Bollinsure will provide the appropriate client-included introduction or secure document path after reviewing the request.

Common questions

A clean professional boundary.

What happens when I introduce a client?

A named licensed Bollinsure broker establishes the insurance scope directly with the client, gives the client a written next action, and shares limited status with the referring professional only when the client permits it.

What information is needed to begin?

The client or business name, the insurance trigger, and any real deadline are enough to start. Sensitive financial, medical, employee, or account records are not needed for the initial handoff.

Does the partnership require referrals or compensation?

No referral fee, reciprocal introduction, or production commitment is assumed. Any proposed compensation arrangement must be reviewed and documented separately before use.

How early should a buyer investigate insurance?

As soon as the property and intended use are known, especially for wildfire exposure, older construction, unusual occupancy, prior non-renewal, or a short financing contingency.